TeamEmond

Lakeville Real Estate

Welcome to TeamEmond

  • Home
  • Search
  • Our Listings
  • News
  • About TeamEmond
  • Contact

Why This Summer Is the 2020 Real Estate Season

May 27, 2020 by teamemond

Why This Summer Is the 2020 Real Estate Season | Simplifying The Market

With stay-at-home orders starting to gradually lift throughout parts of the country, data indicates homebuyers are jumping back into the market. After many families put their plans on hold due to the COVID-19 pandemic, what we once called the busy spring real estate season is shifting into the summer. In 2020, summer is the new spring for real estate.

Joel Kan, Economist at The Mortgage Bankers Association (MBA) notes:

“Applications for home purchases continue to recover from April’s sizable drop and have now increased for five consecutive weeks…Government purchase applications, which include FHA, VA, and USDA loans, are now 5 percent higher than a year ago, which is an encouraging turnaround after the weakness seen over the past two months.”

Additionally, according to Google Trends, which scores search terms online, searches for real estate increased from 68 points the week of March 15th to 92 points last week. As we can see, more potential homebuyers are looking for homes virtually.

What’s the Opportunity for Buyers?

Another reason buyers are coming back to the market, even with forced unemployment and stay-at-home orders, is historically low mortgage rates. Sam Khater, Chief Economist at Freddie Mac indicates:

“For the fourth consecutive week, the 30-year fixed-rate mortgage has been below 3.30 percent, giving potential buyers a good reason to continue shopping even amid the pandemic…As states reopen, we’re seeing purchase demand improve remarkably fast, now essentially flat relative to a year ago.”

With mortgage rates at such low levels and states gradually beginning to reopen, there’s more incentive than ever to buy a home this summer.

What’s the Opportunity for Sellers?

Finding a home to buy, however, is still a challenge, as this spring sellers removed many listings from the market. Though more people are now putting their houses up for sale this month as compared to last month, current inventory is still well below last year’s level.

According to last week’s Weekly Economic and Housing Market Update from realtor.com:

“Weekly Housing Inventory showed continued tightening. New Listings declined 28% compared with a year ago, as sellers grappled with uncertainty and hesitated bringing homes to market. Total Listings dropped 20% YoY, a faster rate than in prior weeks, leaving very few homes available for sale. As Time on Market was 15 days slower YoY, asking prices moved up 1.5% YoY.”

If you’re thinking of selling your house this summer, now may be your best opportunity. With so few homes on the market for buyers to purchase, this season may be the time for your house to stand out from the crowd. Trusted real estate professionals can help you list safely and effectively, keeping your family’s needs top of mind. Buyers are looking, and your house may be at the top of their list.

Bottom Line

If you’re thinking of selling, many buyers may be eager to find a home just like yours. Let’s connect today to make sure you can get your house in on the action this summer.

Filed Under: First Time Home Buyers, For Buyers, For Sellers, Housing Market Updates, Monthly Skinny Video, Move-Up Buyers

Interest Rates Hover Near Historic All-Time Lows [INFOGRAPHIC]

May 22, 2020 by teamemond

Interest Rates Hover Near Historic All-Time Lows [INFOGRAPHIC] | Simplifying The Market

Interest Rates Hover Near Historic All-Time Lows [INFOGRAPHIC] | Simplifying The Market

Some Highlights

  • Mortgage interest rates have dropped considerably this spring and are hovering at a historically low level.
  • Locking in at a low rate today could save you thousands of dollars over the lifetime of your home loan.
  • Let’s connect to determine the best way to position yourself for a move in today’s market.

Filed Under: First Time Home Buyers, For Buyers, Infographics, Monthly Skinny Video

Yes, You Can Still Afford a Home

March 12, 2020 by teamemond

Yes, You Can Still Afford a Home | Simplifying The Market

The residential real estate market has come roaring out of the gates in 2020. Compared to this time last year, the number of buyers looking for a home is up 20%, and the number of home sales is up almost 10%. The increase in purchasing activity has caused home price appreciation to begin reaccelerating. Many analysts have boosted their projections for price appreciation this year.

Whenever home prices begin to increase, there’s an immediate concern about how that will impact the ability Americans have to purchase a home. That thinking is understandable. We must, however, realize that price is not the only element to the affordability equation. Mark Fleming, Chief Economist at First American, recently explained:

“When demand increases for a scarce (limited or low supply) good, prices will rise faster. The difference between houses and other goods is that we buy them with a mortgage. So, it’s not the actual price that matters, but the price relative to purchasing power.”

While home prices have risen recently, mortgage interest rates have fallen rather dramatically. At the beginning of last year, the 30-year fixed-rate mortgage stood at 4.46%. Today, that number stands over a full percentage point lower.

How does a lower mortgage rate impact your monthly mortgage payment?

Michael Hyman, a research data specialist for the National Association of Realtors (NAR), explained in a recent report that, even though home values have increased over the last year, the monthly cost of owning a home has decreased:

“With lower mortgage rates compared to one year ago, the payment as a percentage of income fell to 15.5%…from 17.1% a year ago.”

When purchasing a home, the price is not as important as its cost. Today, the monthly expense (cost) of purchasing the same house you could have purchased last year would be less. Or, you could purchase a more expensive home for the same monthly expense.

Fleming, looking at all aspects of the affordability equation (prices, wages, and mortgage rates), calculated the actual numbers in a recent blog post:

“Low mortgage rates and income growth triggered a 13.5% increase in house-buying power compared with a year ago.”

Since wages have increased and mortgage rates have dropped to historically low levels, this is a great time to buy your first home or move up to the home of your dreams. As Tendayi Kapfidze, Chief Economist at LendingTree, recently advised:

“If you are in a point in your life where you’re considering buying a home today, it’s a better time to buy than 10 years ago. If you can get a mortgage, you’re getting much lower interest rates, and it enables you to afford more.”

Bottom Line

Whether you’ve considered becoming a homeowner for the first time or have decided to sell your home and buy one that better suits your current lifestyle, now is a great time to get together and discuss your options.

Filed Under: First Time Home Buyers, For Buyers, Monthly Skinny Video, Move-Up Buyers, Pricing

How Interest Rates Can Impact Your Monthly Housing Payments

March 3, 2020 by teamemond

How Interest Rates Can Impact Your Monthly Housing Payments | Simplifying The Market

Spring is right around the corner, so flowers are starting to bloom, and many potential homebuyers are getting ready to step into the market. If you’re thinking of buying this season, here’s how mortgage interest rates are working in your favor.

Freddie Mac explains:

“If you’re in the market to buy a home, today’s average mortgage rates are something to celebrate compared to almost any year since 1971…

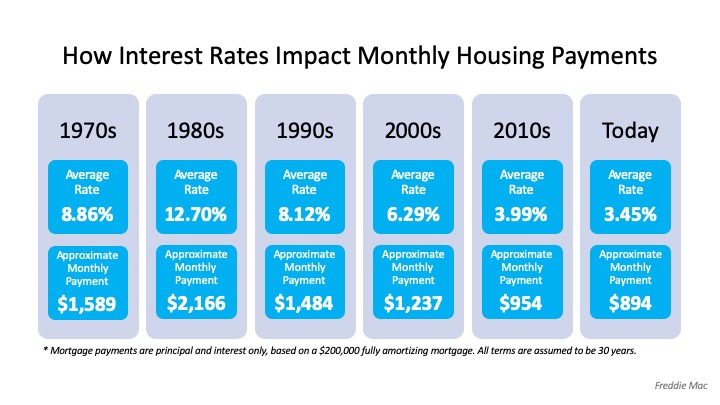
Mortgage rates change frequently. Over the last 45 years, they have ranged from a high of 18.63% (1981) to a low of 3.31% (2012). While it’s not likely that the average 30-year fixed mortgage rate will return to its record low, the current average rate of 3.45% is pretty close — all to your advantage.”

To put this in perspective, the following chart from the same article shows how average mortgage rates by decade have impacted the approximate monthly payment of a $200,000 home over time:How Interest Rates Can Impact Your Monthly Housing Payments | Simplifying The MarketClearly, when rates are low – like they are today – qualified buyers can benefit significantly over time.

Keep in mind, if interest rates go up, this can push many potential homebuyers out of the market. The National Association of Home Builders (NAHB) notes:

“Prospective home buyers are also adversely affected when interest rates rise. NAHB’s priced-out estimates show that, depending on the starting rate, a quarter-point increase in the rate of 3.75% on a 30-year fixed rate mortgage can price over 1.3 million U.S. households out of the market for the median-priced new home.”

Bottom Line

You certainly don’t want to be priced out of the market this year, and waiting may mean a significant change in your potential mortgage payment should rates start to rise. If your financial situation allows, now may be a great time to lock in at a low mortgage rate to benefit greatly over the lifetime of your loan.

Filed Under: First Time Home Buyers, For Buyers, Monthly Skinny Video, Move-Up Buyers

Interest Rates Over Time [INFOGRAPHIC]

February 21, 2020 by teamemond

Interest Rates Over Time [INFOGRAPHIC] | Simplifying The Market

Interest Rates Over Time [INFOGRAPHIC] | Simplifying The Market

Some Highlights:

  • With interest rates hovering at near historic lows, now is a great time to look back at where they’ve been, and how much they’ve changed over time.
  • According to Freddie Mac, mortgage interest rates are currently hovering near a five-decade low.
  • The impact your interest rate has on your monthly mortgage payment is significant. An increase of just $20 dollars in your monthly payment can add up to $240 per year or $7,200 over the life of your loan. Maybe it’s time to lock in now while rates are still low.

Filed Under: For Buyers, Infographics, Monthly Skinny Video

The #1 Misconception in the Homebuying Process

February 20, 2020 by teamemond

The #1 Misconception in the Homebuying Process | Simplifying The Market

After over a year of moderating home prices, it appears home value appreciation is about to reaccelerate. Skylar Olsen, Director of Economic Research at Zillow, explained in a recent article:

 “A year ago, a combination of a government shutdown, stock market slump and mortgage rate spike caused a long-anticipated inventory rise. That supposed boom turned out to be a short-lived mirage as buyers came back into the market and more than erased the inventory gains. As a natural reaction, the recent slowdown in home values looks like it’s set to reverse back.”

CoreLogic, in their January 2020 Market Pulse Report, agrees with Olsen, projecting home value appreciation in all fifty states this year. Here’s the breakdown:

  • 21 states appreciating 5% or more
  • 26 states appreciating between 3-5%
  • Only 3 states appreciating less than 3%

The Misconception

Many believe when real estate values are increasing, owning a home becomes less affordable. That misconception is not necessarily true.

In most cases, homes are purchased with a mortgage. The current mortgage rate is a major component of the affordability equation. Mortgage rates have fallen by almost a full percentage point since this time last year.

Another major piece of the equation is a buyer’s income. The median family income has risen by 5% over the last year, contributing to the affordability factor.

Black Knight, in their latest Mortgage Monitor, addressed this exact issue:

 “Despite the average home price increasing by nearly $13,000 from just over a year ago, the monthly mortgage payment required to buy that same home has actually dropped by 10% over that same span due to falling interest rates…

Put another way, prospective homebuyers can now purchase a $48K more expensive home than a year ago while still paying the same in principal and interest, a 16% increase in buying power.”

Bottom Line

If you’re thinking about purchasing a home, realize that homes are still affordable even though prices are increasing. As the Black Knight report concluded:

“Even with home price growth accelerating, today’s low-interest-rate environment has made home affordability the best it’s been since early 2018.”

Filed Under: Buying Myths, For Buyers, Monthly Skinny Video, Pricing

  • « Previous Page
  • 1
  • …
  • 57
  • 58
  • 59
  • 60
  • 61
  • …
  • 68
  • Next Page »

Realtor & Housing
Licensed In Minnesota

All information deemed reliable but not guaranteed and should be independently verified.

By searching you agree to the end user license agreement.

DMCA Copyright Notice.

Copyright © 2026 | MSLLC